Introduction: Are You Building Wealth Without Building Financial Security?
Imagine this situation.
You have started investing regularly in mutual funds. Your SIPs are running smoothly, your portfolio is growing and you are excited about your financial future.
Suddenly, an unexpected medical expense arises. Or you face a temporary loss of income, an urgent home repair or an unforeseen family responsibility.
You need money immediately.
What happens next?
If you do not have sufficient savings readily available, you may be forced to withdraw your investments, stop your SIPs or borrow money at an unfavourable interest rate.
This is where an important financial planning principle becomes relevant:
Before you focus on growing your wealth, build a financial safety net that protects it.
Many investors concentrate on selecting mutual funds, comparing returns and starting SIPs. However, they sometimes overlook one of the most basic foundations of financial security: an emergency fund.
An emergency fund may not generate exciting returns, but its purpose is far more important. It provides financial support when life does not go according to plan.
1. What Is an Emergency Fund?
An emergency fund is money kept separately to meet unexpected and unavoidable financial expenses.
It is not meant for holidays, shopping, lifestyle upgrades or planned purchases.
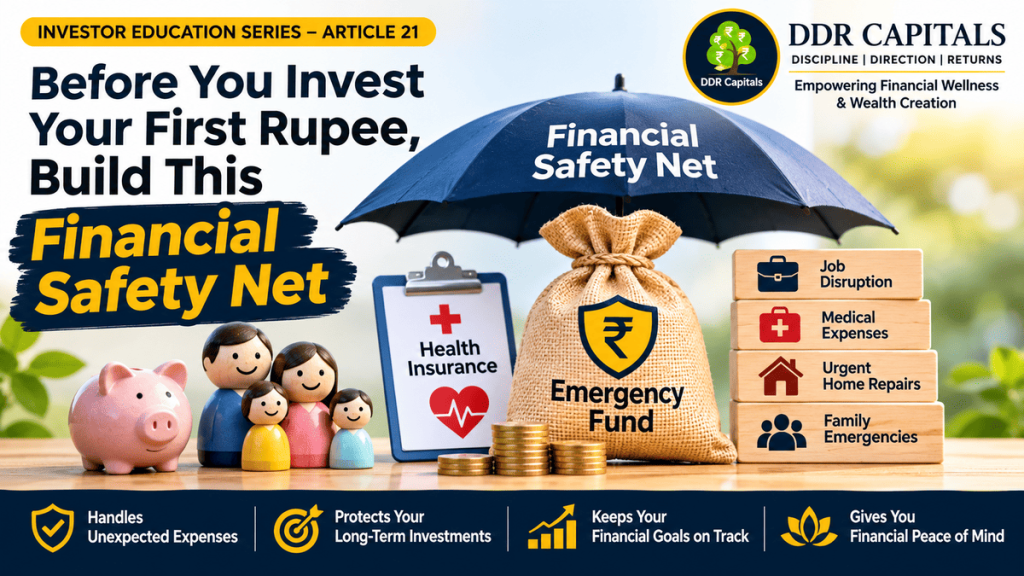
It is a financial reserve designed to help you manage situations such as:
- Sudden loss of employment or business income.
- Unexpected medical or hospital expenses.
- Urgent home or vehicle repairs.
- Essential family emergencies.
- Temporary disruption in business cash flow.
- Unplanned expenses that cannot reasonably be postponed.
The purpose is to ensure that an unexpected expense does not disturb your long-term investment strategy.
Think of an emergency fund as a financial cushion between you and life’s uncertainties.
2. Why Should You Build an Emergency Fund Before Investing?
Investments are generally made with specific financial objectives and time horizons.
For example, equity mutual funds may be considered for long-term goals, while other investments may be more suitable for shorter-term requirements depending on their risk and liquidity characteristics.
But emergencies do not follow investment timelines.
You may need money at a time when financial markets are declining.
Imagine that you have invested ₹5 lakh in an equity mutual fund. Due to an unexpected medical expense, you need ₹1 lakh immediately.
If the market is experiencing a correction, you may have to redeem units at an unfavourable valuation.
The problem is not necessarily the investment itself. The problem is that money required for emergencies was not kept separately.
An adequate emergency reserve can help you:
- Avoid premature redemption of long-term investments.
- Continue planned investments during temporary difficulties, if affordable.
- Reduce dependence on high-cost borrowing.
- Manage unexpected expenses with greater confidence.
- Protect your financial goals from short-term disruptions.
An emergency fund does not replace investing. It creates a stronger foundation for investing.
3. How Much Emergency Fund Should You Maintain?
There is no single amount suitable for every individual.
A commonly used starting guideline is to maintain approximately three to six months of essential household expenses.
However, the appropriate amount depends on your income stability, family responsibilities, health coverage, dependants and other financial commitments.
For some households, a larger reserve may be appropriate.
Consider the following illustration.
Suppose your essential monthly household expenses are:
| Expense | Monthly amount |
|---|---|
| Household expenses | ₹20,000 |
| Rent or housing expenses | ₹12,000 |
| Utilities and communication | ₹3,000 |
| Medical and essential insurance costs | ₹5,000 |
| Education and family commitments | ₹10,000 |
| Transport and essential travel | ₹5,000 |
| Total monthly essentials | ₹55,000 |
Based on these illustrative expenses:
| Emergency reserve period | Required amount |
|---|---|
| 3 months | ₹1,65,000 |
| 6 months | ₹3,30,000 |
| 9 months | ₹4,95,000 |
| 12 months | ₹6,60,000 |
An individual with stable employment and limited financial responsibilities may consider a smaller reserve.
A self-employed professional, business owner, single-income household or person with several dependants may need a larger reserve.
The objective is not to follow a fixed formula blindly. It is to maintain enough accessible money to manage a realistic period of financial disruption.
4. Who Needs a Larger Emergency Fund?
Different households face different financial risks.
Salaried employees
Individuals with stable employment may begin with a reserve covering three to six months of essential expenses, depending on their circumstances.
Self-employed professionals
Income may fluctuate from month to month. A reserve covering six to twelve months of essential expenses may be worth considering.
Business owners
Business cash flow can be unpredictable. Personal emergency savings should be maintained separately from business working capital.
Single-income families
When several family members depend on one person’s income, a larger reserve may provide additional protection.
Retired individuals
Retirees should consider predictable household expenses, medical requirements, insurance coverage and the liquidity needs of their retirement income plan.
Individuals with dependants
Parents supporting children or individuals financially responsible for elderly family members should account for these commitments when deciding the appropriate reserve.
Your emergency fund should reflect your financial responsibilities, not someone else’s formula.
5. Where Should You Keep Your Emergency Fund?
An emergency fund has a different purpose from a long-term investment portfolio.
Its primary objectives are:
- Safety of capital.
- Easy access to money.
- Liquidity when required.
- Reasonable stability of value.
Suitable options may include:
A. Savings bank account
When choosing a bank account or deposit, understand the applicable deposit protection, account terms and withdrawal conditions.
A savings account provides convenient access to funds through banking channels, subject to applicable account limits and transaction arrangements.
It is useful for maintaining the immediately accessible portion of an emergency reserve.
B. Sweep-in or auto-sweep fixed deposit
Some banks provide facilities that link a savings account with fixed deposits.
Depending on the bank’s terms, funds can be accessed when required while the remaining balance may earn a different rate of interest.
Check premature withdrawal rules, minimum balances and applicable charges.
C. Short-term bank fixed deposits
Bank fixed deposits with appropriate tenures may be considered for money that is not required immediately.
Before selecting them, understand premature withdrawal conditions, penalties and access arrangements.
D. Liquid mutual funds
Liquid mutual funds invest primarily in short-term money-market and debt instruments.
They may be considered for a portion of the reserve after understanding their market, credit and liquidity risks.
They are not bank deposits, are not guaranteed and do not provide assured returns.
For emergency money, convenience and capital safety should generally take priority over chasing higher returns.
Redemption proceeds are subject to the applicable scheme terms, cut-off timings and settlement process, so investors should not assume that the entire amount will always be available instantly.
An emergency fund should not depend entirely on investments whose value may fluctuate or whose redemption may take time.
6. Should You Keep Your Entire Emergency Fund in One Place?
Not necessarily.
A practical approach may be to divide the reserve according to how quickly the money could be required.
For example, consider a household with a target emergency reserve of ₹3 lakh.
An illustrative arrangement could be:
| Allocation | Amount | Purpose |
|---|---|---|
| Savings account | ₹75,000 | Immediate requirements |
| Sweep-in or short-term FD | ₹1,50,000 | Near-term emergencies |
| Liquid fund | ₹75,000 | Additional reserve, subject to redemption terms and risks |
| Total | ₹3,00,000 |
This is only an illustration, not a recommended allocation for every investor.
The actual arrangement should depend on access requirements, bank terms, financial circumstances and the investor’s understanding of the risks involved.
The important point is to avoid placing all emergency money in an instrument that may be difficult to access when needed.
7. Emergency Fund and Health Insurance: Do You Need Both?
Yes. They serve different purposes.
Health insurance provides financial protection against covered medical expenses, subject to policy terms, exclusions, waiting periods, limits and other conditions.
An emergency fund provides money for expenses that insurance may not cover and for non-medical emergencies.
For example, even with health insurance, a family may have to meet:
- Policy deductibles or co-payments.
- Non-payable or excluded expenses.
- Costs exceeding policy limits.
- Immediate medical-related travel expenses.
- Household expenses during recovery.
Similarly, health insurance cannot replace the income lost during a period of unemployment or business disruption.
Therefore, insurance and emergency savings should be viewed as complementary parts of financial preparedness.
8. Five Common Mistakes Investors Make With Emergency Funds
Mistake 1: Investing all available savings
Some investors start SIPs or make lump-sum investments without first setting aside sufficient emergency money.
This can create liquidity pressure when unexpected expenses arise.
Mistake 2: Keeping emergency money in equity investments
Equity investments can experience market fluctuations. Their value may be lower precisely when emergency money is needed.
Mistake 3: Chasing higher returns
The primary purpose of an emergency fund is financial protection, not maximum returns.
Choosing an instrument purely because it offers a higher expected return may introduce unnecessary risk or reduce accessibility.
Mistake 4: Using the emergency fund for planned purchases
A holiday, new smartphone or lifestyle upgrade is generally not an emergency.
Using the reserve for such expenses weakens your financial protection.
Mistake 5: Never replenishing the emergency fund
If you use the reserve for a genuine emergency, make replenishing it a priority once your financial circumstances permit.
An emergency fund is not a one-time exercise. It requires periodic attention.
9. How Can You Build an Emergency Fund If You Have Limited Savings?
You do not need to accumulate the entire amount immediately.
Start with a realistic target and build it gradually.
Consider the following steps:
Step 1: Calculate essential monthly expenses
Separate necessary expenses from discretionary spending.
Step 2: Set your initial target
Start with a manageable amount, such as one month’s essential expenses.
Step 3: Create a separate savings arrangement
Keep emergency money separate from your regular spending account so that it is less likely to be used casually.
Step 4: Automate regular contributions
Set aside a fixed amount every month after receiving your income.
Step 5: Increase contributions when possible
Salary increases, bonuses, additional business income or reductions in discretionary expenses may help you build the reserve faster.
Step 6: Review your target periodically
If your household expenses or financial responsibilities increase, your emergency fund target may also need to increase.
Consistency matters more than trying to build the entire reserve in one month.
10. Should You Stop Your SIP Until Your Emergency Fund Is Complete?
This depends on your financial circumstances.
If you have no emergency savings and are struggling to meet essential expenses, building basic liquidity should generally receive priority.
However, someone with stable income, adequate insurance and an existing reserve may be able to continue investing while gradually strengthening the emergency fund.
There is no universal answer.
A balanced financial plan should consider:
- Existing emergency savings.
- Monthly income and expenses.
- Outstanding loans and financial obligations.
- Insurance coverage.
- Family responsibilities.
- Investment goals and time horizons.
The objective is to avoid creating a situation where you are investing for the future while remaining financially unprepared for the present.
11. When Should You Use Your Emergency Fund?
An emergency fund should be used for genuine, unexpected and necessary financial requirements.
Examples include:
- Sudden loss of income.
- Unplanned medical expenses.
- Essential urgent repairs.
- Unexpected family emergencies.
- Necessary expenses during a temporary business disruption.
It should generally not be used for:
- Vacations.
- Festivals and celebrations.
- Planned shopping.
- Speculative investments.
- Taking advantage of a temporary stock-market correction.
- Lifestyle upgrades.
A useful question to ask before using the fund is:
Is this expense unexpected, necessary and urgent?
If the answer is no, consider whether it should be funded through your regular savings instead.
12. Your Financial Safety Net Should Grow With Your Life
Your financial responsibilities are unlikely to remain unchanged throughout your life.
A person starting their career may have limited household commitments.
After marriage, the financial situation may change. The arrival of children, a home loan, dependent parents or business responsibilities can increase the amount of money required during an emergency.
Therefore, your emergency fund should be reviewed when significant life changes occur.
Regularly reviewing your financial arrangements is equally important. Read our related article: When Should You Review Your Mutual Fund Portfolio? to understand why periodic portfolio reviews matter.
For example:
- A salary increase may lead to higher household expenses.
- A new home loan may increase monthly commitments.
- Starting a business may make income less predictable.
- Having children may increase financial responsibilities.
- Retirement may require a different liquidity arrangement.
An emergency fund should evolve along with your financial life.
13. A Simple Financial Safety Net Checklist
Before concentrating on wealth creation, ask yourself these questions:
- Have I calculated my essential monthly household expenses?
- Do I have readily accessible emergency savings?
- Can my reserve cover at least three to six months of essential expenses?
- Is my emergency fund appropriate for my income stability?
- Do I have adequate health insurance?
- Are my emergency savings separate from my investment portfolio?
- Can I access the money without unnecessary delay or penalties?
- Do I understand the risks and withdrawal terms of the instruments I use?
- Do I have a plan to replenish the reserve after using it?
- Have I reviewed my emergency fund after major life changes?
If you cannot answer these questions confidently, strengthening your financial safety net may be a sensible first step. A structured approach can help you make more informed financial decisions. You may also find our article The Power of an Investment Checklist: Think Before You Invest useful.
14. Build Financial Security Before Chasing Higher Returns
Many investors begin their financial journey by asking:
Which mutual fund should I invest in?
Which investment offers better returns?
How much wealth can I create through an SIP?
These are relevant questions, but they should not be the only questions.
A stronger financial foundation begins with understanding your income, expenses, liabilities, insurance protection, liquidity requirements and financial goals.
An emergency fund may not make your investment portfolio look impressive. It may not generate the returns discussed in market headlines.
But when an unexpected financial challenge arises, it can provide something extremely valuable: the ability to meet essential expenses without unnecessarily disturbing your long-term financial plans.
Wealth creation begins with financial discipline. Financial discipline begins with financial preparedness.
15. Key Takeaways
- An emergency fund is an essential part of financial preparedness.
- It helps manage unexpected expenses and temporary income disruptions.
- A common starting guideline is three to six months of essential expenses.
- Self-employed individuals, business owners and households with dependants may need a larger reserve.
- Emergency money should prioritise safety, liquidity and accessibility.
- Savings accounts, suitable bank deposits and certain liquid investment options may serve different parts of the reserve.
- Liquid mutual funds are market-linked products and are not guaranteed deposits.
- Health insurance and emergency savings serve different but complementary purposes.
- Avoid using emergency savings for planned lifestyle expenses or speculative investments.
- Review and replenish your emergency fund as your financial responsibilities change.
Final Thought
Before you invest your first rupee, ask yourself one important question:
If my income stopped tomorrow or an unexpected expense arose today, would my family remain financially secure?
If the answer is uncertain, building an emergency fund deserves your attention.
Do not focus only on how fast your wealth can grow. Also consider how well you can protect your financial plans when life becomes unpredictable.
Build your safety net first. Invest with greater confidence. Create wealth with discipline.
About the Author
Mrs. Mansi Radadia , Operations & Compliance Officer, DDR Capitals. Contributor – Investor Education Series. With a strong focus on investor servicing, operational excellence and regulatory compliance, she is committed to helping investors navigate their financial journey with confidence. She believes successful wealth creation is built on discipline, informed decision-making and staying invested through changing market cycles. She actively supports investor education initiatives and encourages investors to explore Investor Education Resources.
About DDR Capitals
DDR Capitals is committed to empowering financial wellness and wealth creation through investor education and financial product distribution. Through its Investor Education Series, DDR Capitals shares practical information to help investors understand investment concepts, develop financial awareness and make informed financial decisions.
Disclaimer
This article is intended solely for investor education and general awareness. It should not be construed as investment advice, a recommendation, or a solicitation to buy or sell any financial product or security.
Investments in securities and mutual funds are subject to market risks. Read all scheme-related documents carefully before investing. Past performance does not guarantee future returns. Investors should assess their financial objectives, risk profile, liquidity requirements and investment horizon before making investment decisions.