Introduction
Investment goals are rarely limited to just one purpose.
Most investors do not invest for just one reason. Investment goals are rarely limited to just one purpose.
The same investor may be saving for retirement, planning a child’s education, considering a home purchase, building a business reserve, preparing for a major future expense, and also wanting to create long-term wealth.
Yet there is often one common problem:
All the investments sit together in one portfolio — without a clear connection to the goals they are meant to serve.
The portfolio may look diversified. It may contain mutual funds, stocks, fixed-income investments and other assets.
But diversification alone does not answer an important question:
Which part of your portfolio is meant for which goal?
When multiple goals are mixed together, it can become difficult to know whether you are taking too much risk, investing for the right time horizon, or making progress toward what actually matters.
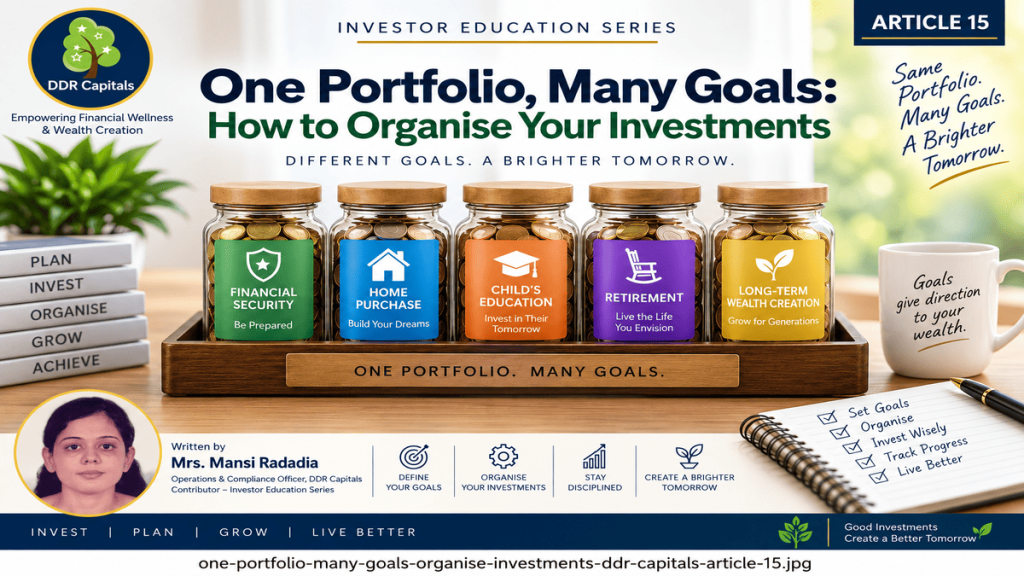
A more organised approach is to think of your portfolio as one overall wealth structure containing several goal-based investment buckets.
Why One Portfolio Can Become Confusing
Imagine an investor has ₹1 crore invested across different assets.
At first glance, this may appear to be a substantial and diversified portfolio.
But suppose that same ₹1 crore is intended for:
- Retirement in 10 years
- Child’s education in 4 years
- A home purchase in 3 years
- Emergency or family requirements
- Long-term wealth creation
These goals do not have the same:
Time horizon.
Risk capacity.
Liquidity requirement.
Priority.
So treating the entire ₹1 crore in exactly the same way may not be appropriate.
The investment strategy for money required in three years may need to be considered differently from money intended for a goal 15 years away.
This is where goal-based organisation becomes useful.
One Portfolio Does Not Mean One Strategy
Having one consolidated portfolio is perfectly normal.
But inside that portfolio, different portions of your money can have different purposes.
Think of it this way:
ONE WEALTH PORTFOLIO
↓
Goal 1 → Retirement
Goal 2 → Education
Goal 3 → Home
Goal 4 → Financial Security
Goal 5 → Long-Term Wealth Creation
Each goal can then be evaluated separately.
The purpose is not necessarily to create five completely separate investment accounts.
The purpose is to create clarity about what each portion of your wealth is expected to accomplish.
Step 1: List All Your Important Financial Goals
Before deciding where money should be invested, identify your investment goals and what each portion of your money is actually intended to accomplish
Start with a simple list.
| Financial Goal | Approximate Time Horizon | Priority |
|---|---|---|
| Emergency / Financial Security | Immediate | High |
| Home Purchase | 3–5 years | High |
| Child’s Education | 5–10 years | High |
| Retirement | 10–20 years | High |
| Long-Term Wealth Creation | 15+ years | Medium / Long-term |
The exact goals will differ from investor to investor.
The important point is to name the goal before evaluating the investment.
Step 2: Give Every Goal a Time Horizon
Time is one of the most important factors in investment planning.
A goal that is only two years away gives you much less time to recover from a significant market decline than a goal that is fifteen years away.
Consider two investors:
Investor A
Needs ₹25 lakh in three years for a home purchase.
Investor B
Needs ₹25 lakh in fifteen years for retirement.
The amount is the same.
But the time available is very different.
That difference can materially affect how the money should be organised.
A useful question is:
When will I actually need this money?
Not:
Understanding the time horizon of different investment goals can help investors organise their portfolio more effectively.
“What investment is giving the highest return today?”
Step 3: Understand the Difference Between Risk Tolerance and Risk Capacity
This is especially important when you have multiple goals.
Risk tolerance is about how comfortable you are with fluctuations and potential losses.
Risk capacity is about how much financial risk you can realistically afford to take without jeopardising an important goal.
These are not the same thing.
An investor may have a high tolerance for market volatility but still have low risk capacity for money required shortly for an important expense.
For example, an investor may be comfortable with equity-market fluctuations in general.
But if ₹20 lakh is required in two years for a child’s education, the ability to take substantial risk with that particular money may be limited.
Therefore:
Your portfolio should consider not only who you are as an investor, but also what each portion of your money needs to accomplish.
This is particularly important when different investment goals have different deadlines
Step 4: Create Goal-Based Buckets
Once your investment goals and time horizons are identified, organise the portfolio into practical buckets.
For example:
🛡️ Bucket 1 — Financial Security
Purpose:
- Emergency needs
- Unexpected expenses
- Near-term financial commitments
Priority:
Liquidity and stability
🏠 Bucket 2 — Short-to-Medium-Term Goals
Purpose:
- Home purchase
- Vehicle purchase
- Major family expenses
- Other planned requirements
Priority:
Goal visibility, liquidity and appropriate risk
🎓 Bucket 3 — Medium-to-Long-Term Goals
Purpose:
- Children’s education
- Major future commitments
Priority:
Balancing growth potential with the approaching goal deadline
🌱 Bucket 4 — Long-Term Wealth Creation
Purpose:
- Retirement
- Legacy planning
- Long-term wealth accumulation
Priority:
Long-term growth and disciplined investing
The Important Point: Buckets Are Not Just About Asset Classes
Goal-based organisation does not mean simply saying:
Equity = Long-term
Debt = Short-term
Real portfolios can be more nuanced.
The appropriate investment structure depends on several factors, including:
- Goal amount
- Time horizon
- Risk tolerance
- Risk capacity
- Liquidity requirements
- Existing assets
- Income and cash flows
- Other financial commitments
The objective is to create an investment structure that makes sense for the goal, rather than selecting an investment first and trying to find a goal for it afterward.
Step 5: Calculate the Gap — Not Just the Current Value
One common mistake is to look at the current portfolio value and feel comfortable because the number looks large.
Instead, ask:
How much do I actually need for the goal?
Suppose:
Current retirement corpus: ₹50 lakh
Estimated retirement requirement: ₹1.5 crore
The important number is not simply ₹50 lakh.
Each of your major investment goals should therefore be evaluated against the amount required, the current corpus and the time remaining.
The important question is:
How large is the gap, and how much time remains?
This changes the conversation from:
“How is my portfolio performing?”
to:
“Am I making reasonable progress toward my goal?”
That is a much more useful question.
Step 6: Separate Goal Progress From Portfolio Performance
A portfolio can generate a good return and still make poor progress toward an important goal.
For example, an investment may generate a strong return over one year.
But if the investor’s goal requires a particular amount by a particular date, the relevant question is whether the investment strategy is helping the investor move toward that target.
This is why:
Return is a measurement.
Goal progress is the purpose.
Both matter.
But they answer different questions.
Step 7: Avoid Using One Goal to Fund Another Without Thinking
Multiple goals can compete for the same pool of money.
For example:
You may have ₹30 lakh invested.
At the same time:
- Your child needs education funding in four years.
- You are planning retirement.
- You are considering buying a property.
If you withdraw a large amount for one goal, you may unintentionally reduce the resources available for another.
Therefore, every major withdrawal should trigger a simple question:
What happens to my other goals if I use this money now?
This is one of the benefits of organising investments by purpose.
Step 8: Review Each Bucket Separately
A portfolio review should not only ask:
“Which investment performed best?”
Instead, review each goal:
Goal Review
1. What is the goal?
2. How much money may be required?
3. When will the money be needed?
4. How much has already been accumulated?
5. How much more needs to be invested?
6. Has my financial situation changed?
7. Does the current investment structure still make sense for the goal?
This approach turns portfolio review into a goal-progress review, rather than simply a return comparison. A useful portfolio review should examine whether each investment goal remains on track.
What Happens When Goals Are Not Organised?
When investments are not connected to specific goals, several problems can arise.
1. You may take too much risk
A near-term goal may remain exposed to unnecessary market volatility.
2. You may take too little risk
A very long-term goal may not have enough growth-oriented exposure to keep pace with its requirements.
3. You may chase returns
You may move money toward whichever investment performed well recently.
4. You may panic during market corrections
A falling portfolio can feel much more frightening when you do not know what the money is actually meant for.
5. You may spend money meant for another goal
Without clear boundaries, one financial priority can quietly consume another.
One Investor Can Have Different Investment Personalities for Different Goals
This connects directly with Article 13: Your Investment Portfolio Has a Personality — Does It Match Yours?
You may personally be comfortable with market volatility.
But that does not mean every rupee you own should be invested with the same level of risk.
Your retirement money may have a long horizon.
Your child’s education money may have a shorter horizon.
Your emergency reserve may have an immediate requirement.
The investor is one person.
The goals are different.
The investment structure may therefore be different.
A Simple Goal-Based Portfolio Map
Consider creating a simple table like this:
| Goal | Time Horizon | Amount Required | Current Corpus | Monthly Contribution | Review |
|---|---|---|---|---|---|
| Emergency Reserve | Immediate | ₹X | ₹X | ₹X | Regular |
| Home Purchase | 3–5 years | ₹X | ₹X | ₹X | Periodic |
| Education | 5–10 years | ₹X | ₹X | ₹X | Periodic |
| Retirement | 10–20 years | ₹X | ₹X | ₹X | Regular |
| Wealth Creation | 15+ years | ₹X | ₹X | ₹X | Periodic |
You don’t need complicated software to begin.
Even a simple spreadsheet can provide a completely different level of clarity.
The Five-Minute Multi-Goal Portfolio Check
Take five minutes and ask yourself:
1️⃣ What are my top investment goals?
Can I name them clearly?
2️⃣ When will I need the money?
Does every major investment have a time horizon?
3️⃣ Which investments are linked to each goal?
If I don’t know, why am I holding them?
4️⃣ Which goals are ahead or behind schedule?
Am I making reasonable progress?
5️⃣ Has anything changed?
Have my income, expenses, family responsibilities, time horizon or priorities changed?
If you cannot answer these questions, your portfolio may need better organisation rather than more investments.
The Goal Is Not More Investments. It Is More Clarity.
A common misconception is that organising a portfolio means adding more funds, more stocks or more products.
It doesn’t.
In fact, good organisation can sometimes reveal that you already own enough investments.
The real improvement may come from understanding:
What you own.
Why you own it.
Which goal it supports.
When you may need the money.
And whether the risk remains appropriate.
That clarity can make portfolio decisions more disciplined.
When Should You Reorganise Your Portfolio?
Your portfolio should not necessarily be changed every time markets move.
But major changes in your life may justify a review.
For example:
- Marriage
- Birth of a child
- Change in income
- Career change
- Retirement approaching
- Major property purchase
- Education requirement
- Change in family responsibilities
- Significant change in financial circumstances
Your goals can change.
Your time horizons can change.
Your risk capacity can change.
Therefore, your portfolio may need to evolve as your life evolves.
Smart Investing Means Giving Every Rupee a Job
A well-organised portfolio does not necessarily mean having dozens of investments.
It means knowing what your money is expected to do.
Some money may provide financial security.
Some may support a near-term goal.
Some may fund education.
Some may build retirement wealth.
Some may remain invested for long-term wealth creation. When your investment goals are clearly defined, your portfolio becomes easier to understand, review and manage.
Different jobs.
Different timelines.
One overall wealth strategy.
Key Takeaways
- One portfolio can contain multiple financial goals.
- Different goals can have different time horizons and risk requirements.
- Risk tolerance and risk capacity are not the same thing.
- Know which portion of your portfolio is intended for which goal.
- Measure progress toward goals, not just investment returns.
- Avoid allowing one goal to unintentionally consume money meant for another.
- Review your portfolio when your financial circumstances or goals change.
- More investments do not necessarily mean a better-organised portfolio.
- Clarity about purpose can improve investment discipline.
- Your portfolio should evolve as your financial life evolves.
The Real Test of a Well-Organised Portfolio
You don’t need to know the value of every investment from memory.
But you should be able to answer three simple questions:
What is this money for?
When will I need it?
Is the way it is invested appropriate for that purpose?
If you can answer these questions clearly, you are no longer looking at your portfolio simply as a collection of investments.
You are looking at it as a structured plan for your financial goals.
And that is a much more meaningful way to think about investing.
Continue Your Investor Education Journey
📖 Article 12: Arhttps://ddrcapitals.com/are-you-investing-for-a-goal-or-just-for-returns/e You Investing for a Goal or Just for Returns?
📖 Article 13: Your Investment Portfolio Has a Personality — Does It Match Yours?
📖 Article 14: The Investmhttps://ddrcapitals.com/investment-mistakes-that-look-smart/ent Mista
Article 15: One Portfolio, Many Goals: How to Organise Your Investments
About the Contributor
Mrs. Mansi Radadia
Operations & Compliance Officer, DDR Capitals
Contributor – Investor Education Series
Mrs. Mansi Radadia , Operations & Compliance Officer, DDR Capitals. Contributor – Investor Education Series. With a strong focus on investor servicing, operational excellence and regulatory compliance, she is committed to helping investors navigate their financial journey with confidence. She believes successful wealth creation is built on discipline, informed decision-making and staying invested through changing market cycles. She actively supports investor education initiatives and encourages investors to explore Investor Education Resources. Through the DDR Capitals Investor Education Series, Mansi Radadia contributes educational content designed to help investors understand important concepts, recognize common behavioural mistakes and approach investing with greater awareness and discipline.
Disclaimer
This article is intended solely for investor education and general awareness. It does not constitute investment advice, a recommendation, solicitation, or an offer to buy or sell any securities or investment products. Investment decisions should be made after considering individual financial circumstances, objectives, risk profile and applicable regulations. Past performance does not guarantee future results. Readers should consult an appropriately qualified professional where required.
DDR Capitals
Empowering Financial Wellness & Wealth Creation